


 We are excited to feature Financial Analyst Intern, Josiah Gornicz, for this month's blog post!
Procrastination, or putting things off until a later time, is a bad habit that everyone has been guilty of at one time or another. Whether it be with work, appointments, or getting together with that old friend you haven't seen in a while, sometimes pushing things forward is easy and convenient. In most cases, the task ends up getting done, on time or otherwise, with only a bit of added frustration, and we move on.
In the case of your personal finances, however, time is a powerful asset. Waiting can have a huge impact on the amount of money you have down the road, a missed tax strategy, or uncertainty about where your money will end up when you are gone. While not every financial planning decision needs to be made immediately to have success, understanding the cost of waiting is vital to help you make informed, intentional choices.
Compounding Interest
Money invested grows in two ways; contributions made to an account and compounding of the money in the account. Contributions are easy; you can put money into an investment one time, ten times or once a month. Those contributions obviously grow the investment over time by themselves. As you put more in, the account grows that much each time. (Pretty difficult arithmetic, I know). Compounding can be explained using contributions. Say you put $100 dollars into a hypothetical account that earns a flat 10% interest per year. After the first year, with no other contributions, you’ll have $110 in the account. Now for the following year, that $110 is the amount that earns 10%. So, you’ll get $11 in interest in the second year. Once again, this doesn’t seem like a groundbreaking concept, until we up the scale and the time horizon.
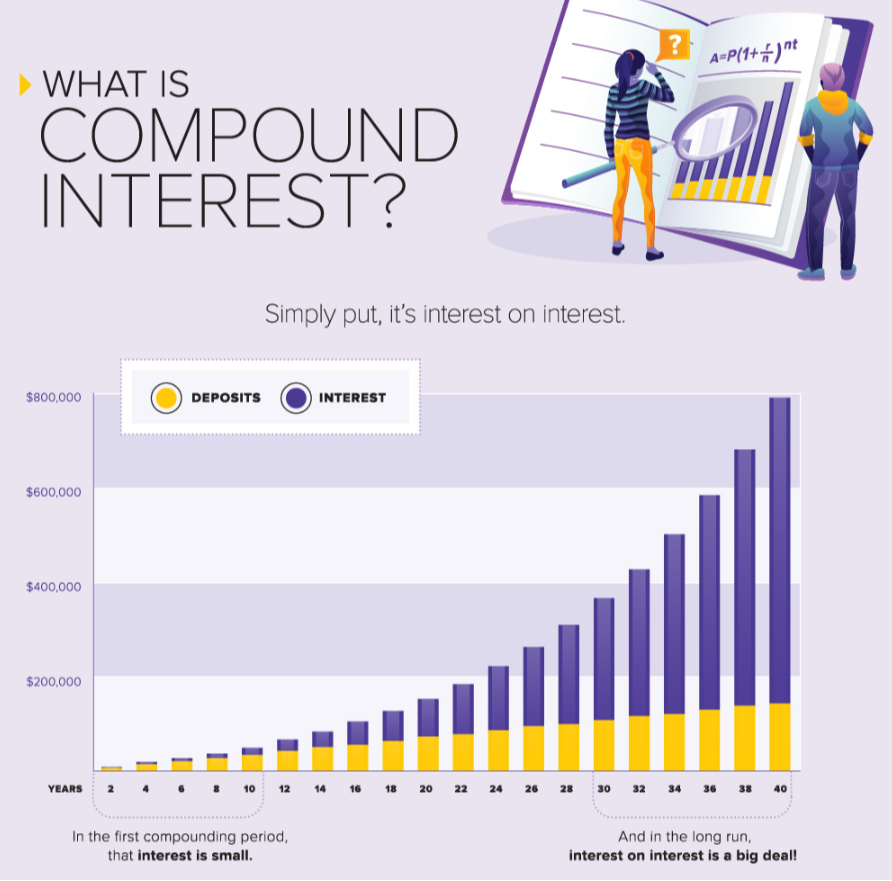
Source (Wealth 101, 2018)
The Brother Experiment
I am 22 and have a younger brother. I went to college and he went into the workforce. Those decisions are a topic for another day, but during the years I’ve been at college, he’s been working, which is important for our example. Say he was able to invest $10,000 at age 20 into that 10% compounding account. Because I was at school, I made the same investment five years later at age 25. If we have the same planning horizon with a retirement age of 65, and don’t touch the account following the initial investment, how much of a difference would the five-year head start really have on our investments?
Well, over the 45 years my brother had, that investment grew to $728,905. That alone should highlight how important time can be, but the point gets driven home even harder. Over the 40 years I had, my investment grew to $452,592. Neither one of those numbers is something to sneeze at, but just a five-year advantage becomes a difference of over $275,000!
With compounding, you are earning returns on your previous returns. That is the beauty of investment markets; you don't need a perfect strategy, you just need to give a good one enough time to grow. Here is the tool I used – Check it out to project investment growth and see compounding at work: Compound Interest Calculator (SEC, 2026).
Other Financial Areas
There are many other ways that waiting can negatively impact your financial situation. Planning your financial life can seem overwhelming, and it certainly can be, especially if you do it all on your own. Getting ahead of things like finding ways to lower taxes, taking advantage of Roth IRAs, or setting up your will can make life that much easier when retirement comes. I won't go into extreme detail about these topics, but that doesn't take away from their importance. We have many detailed explanations in our blog for anyone to access. The further you dig into financial planning aspects, the more you will realize that time is your biggest ally in securing your future, as well as the futures of the next generation.
So, Why Do We Wait?
There are many reasons why people wait to start getting more intentional with their finances. Life’s craziness compounds just like an investment does, financial decisions can be put on the back burner for things that feel more urgent. Some may feel intimidated by the sheer number of choices or decisions, making it easier to leave things alone and never even start. Others may feel like they don’t have enough knowledge or enough money built up yet, so why even bother? All these feelings are completely understandable, but the truth is you don’t need to be approaching retirement or have a certain amount saved to begin your financial journey.
Be Proactive!
Taking little, consistent steps early on will beat waiting the majority of the time. You don’t need a perfect investment strategy to start investing, you don’t need an exact retirement plan to start preparing, and you don’t need to know everything before you take the first step. None of us can go back to start earlier or do things differently. We can decide to start right now, whether it's opening an investment account or researching strategies. Waiting even a little bit longer could be money left on the table. At Whitford, it is our goal to see you succeed!
Thanks for visiting! Schedule an Introductory Call to discuss what you want to accomplish and to see if we are a good fit.